Skip to content
Artwork for Aswath Damodaran
BusinessEntrepreneurshipEducation

Aswath Damodaran

Aswath Damodaran

I teach corporate finance, valuation and investment philosophies at the Stern School of Business at New York University. I have online versions of all three courses here, as well as other finance-related videos.
1. The Corporate Finance Online playlist has an introductory video and 36 sessions that cover all of corporate finance (at least as I see it).
2. The Valuation playlist has 25 sessions that cover valuation approaches, issues and questions.
3. The Investment Philosophies playlist has sessions that cover different investment philosophies.
4. The Accounting and Statistics playlists reflect my quirky and unorthodox introductions to two disciplines that are critical to my valuation and corporate finance classes.
5. The Blog Posts playlist has sessions that go wit my blog posts and reflect my standing as a dabbler, rather than expert, in all things finance-related.
If you need the supporting material for any of the classes, check the links below.

Links:
Corporate finance materials: http://www.stern.nyu.edu/~adamodar/New_Home_Page/corpfin.html
Valuation materials: http://www.stern.nyu.edu/~adamodar/New_Home_Page/equity.html
Investment Philosophies: http://www.stern.nyu.edu/~adamodar/New_Home_Page/invphil.htm
Books: http://www.stern.nyu.edu/~adamodar/New_Home_Page/public.htm
My website: http://www.damodaran.com

Unofficial fan audio feed — not affiliated with or endorsed by the original creator. All content belongs to its respective owner.

Play
  • 246 episodes
  • daily
  • Avg 1 hr
  • English
Counted on this page — what you have heard stays on this device, so it is not something the list can be paged by.
  • October 11 · 1 hr 29 min

    Session 15: More excursions on the dark side of valuation

    In this session, we continued on the dark side of valuation with a look at mature companies on the verge of transitions, and how you have to value the status quo company and the restructured one to make a judgment on investing in it. We then moved on and looked at declining companies, where your forecasts may have to show declining revenues and margins, and added a twist with distressed companies, where you have to follow up your DCF. In the second half of the class we examined the issues (country risk, cross holdings and currency gyrations) that are part of emerging market company valuations and began our assessment of why banks pose special challenge in valuation. Start of the class test: https://www.stern.nyu.edu/~adamodar/pdfiles/eqnotes/tests/dcfvaltests2.pdf Slides: https://www.stern.nyu.edu/~adamodar/podcasts/valspr23/session15slides.pdf Post class test: https://www.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session15Ctest.pdf Post class test solution: https://www.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session15Csoln.pdf Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 10 · 1 hr 25 min

    Session 17: More excursions on the Dark Side of Valuation

    In today’s session, we continued on the dark side of valuation with a look at mature companies on the verge of transitions, and how you have to value the status quo company and the restructured one to make a judgment on investing in it. We then moved on and looked at declining companies, where your forecasts may have to show declining revenues and margins, and added a twist with distressed companies, where you have to follow up your DCF. In the second half of the class we examined the issues (country risk, cross holdings and currency gyrations) that are part of emerging market company valuations and began our assessment of why banks pose special challenge in valuation. In particular, we valued Deutsche Bank in October 2016, and if you are fascinated with this horror story, you may want to read this post from the time: https://aswathdamodaran.blogspot.com/2016/10/deutsche-bank-greek-tragedy-at-german.html tart of the class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/eqnotes/tests/dcfvaltests2.pdf Slides: https://pages.stern.nyu.edu/~adamodar/podcasts/valUGspr23/session17slides.pdf Post class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session17Dtest.pdf Post class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session17Dsoln.pdf Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 10 · 1 hr 34 min

    Session 15: The Tesla Bot Case and Side Benefits/Costs in Projects

    The bulk of this session was spent discussing the Tesla Bot case (see below for the case) and the broader implications for investment and valuation. In the last 30 minutes of class, we turned our attention to the side costs and side benefits in projects, including opportunity costs and synergies and how to incorporate them into decisions. (I am sorry, but I screwed up on sharing the slides for this section for the first 15 minutes or so, but the link to the slides is below as well). Tesla Bot Case: https://pages.stern.nyu.edu/~adamodar/pdfiles/cfexams/TeslaBots.pdf Tesla Bot Presentation: https://pages.stern.nyu.edu/~adamodar/pdfiles/cfexams/TeslaBotPresentation.pdf Slides for rest of class: https://pages.stern.nyu.edu/~adamodar/podcasts/cfspr23/session15slides.pdf Post class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/cfovhds/postclass/session15test.pdf Post class test solution: https://pages.stern.nyu.edu/~adamodar/pdfiles/cfovhds/postclass/session15soln.pdf Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 10 · 26 min

    Active Investing: Rest in Peace or Resurgent Force?

    When Jack Bogle started the Vanguard 500 Index fund in 1975, I am sure that he never visualized how successful he would be. In the last few decades, passive investing has widened its offerings (to include ETFs and other markets) and has taken away market share from active investing, but the pace of disruption seems to have quickened in the last decade. The best advertising for passive investing is the performance of active investors, who seem to lag their passive counterparts, across time, style classes and geographies. I argue that active investing is destined to shrink as a business and that while there are potentially dangerous consequences to the rush to passive investing, the process has its own correction mechanisms. Finally, even in the face of the evidence to the contrary, I explain my rationale for staying an active investor. Slides: http://www.stern.nyu.edu/~adamodar/pdfiles/blog/activeinvesting.pdf Blog Post: http://aswathdamodaran.blogspot.com/2016/12/active-investing-rest-in-peace-or.html Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 10 · 54 min

    Session 16: Closure on Investment Analysis

    In this quiz shortened session, after the quiz, we looked at the final pieces on investment analysis, starting with side benefits from projects (from small pluses to synergy in acquisitions). We also looked at optionality in projects, i.e., times when you can legitimately override conventional investment metrics to take a project, because you may have the option to delay, expand or abandon the project. We then looked back at the process of analyzing projects in place, either for accountability (review forecasts versus actuals) and for decision making (continue, abandon or expand the project). Slides: https://pages.stern.nyu.edu/~adamodar/podcasts/cfspr23/session16slides.pdf Post class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/cfovhds/postclass/session16atest.pdf Post class test solution: https://pages.stern.nyu.edu/~adamodar/pdfiles/cfovhds/postclass/session16asoln.pdf Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 9 · 1 hr

    Session 16: Tying up Intrinsic Value

    In this session, after the second quiz, we wrapped up our discussion of intrinsic valuation. For decades, we have valued banks using the dividend discount model, simply because getting cash flows is so difficult, but that approach is built on trusting management at banks to behave sensibly (paying out what they can afford to in dividends) and regulators to do the same. For me, that trust was breached in 2008, and I present a way of estimating FCFE for a bank, using investment in regulatory capital as my stand in for reinvestment. Next session, we will wrap up the valuation section and start on pricing. If you are interested in reading more about valuing financial service companies, try this link: https://papers.ssrn.com/sol3/papers.cfm?abstract_id=1798578 The Deutsche Bank post is here: http://aswathdamodaran.blogspot.com/2016/10/deutsche-bank-greek-tragedy-at-german.html With SVB’s collapse, which was triggered by duration mismatch, there might be a new iteration that I have to try to bring in that risk into the valuation. We also looked at valuing commodity and cyclical companies, and why capitalizing R&D can change the value of a pharmaceutical company. Slides: https://www.stern.nyu.edu/~adamodar/podcasts/valspr23/session16slides.pdf Post class test: https://www.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session16Ctest.pdf Post class test solution: https://www.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session16Csoln.pdf Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 9 · 49 min

    Session 18: Tying up Intrinsic Value

    In this session, after the second quiz, we wrapped up our discussion of intrinsic valuation. For decades, we have valued banks using the dividend discount model, simply because getting cash flows is so difficult, but that approach is built on trusting management at banks to behave sensibly (paying out what they can afford to in dividends) and regulators to do the same. For me, that trust was breached in 2008, and I present a way of estimating FCFE for a bank, using investment in regulatory capital as my stand in for reinvestment. Next session, we will wrap up the valuation section and start on pricing. If you are interested in reading more about valuing financial service companies, try this link: https://papers.ssrn.com/sol3/papers.cfm?abstract_id=1798578. We also looked at valuing commodity and cyclical companies, and why capitalizing R&D can change the value of a pharmaceutical company. Slides: https://pages.stern.nyu.edu/~adamodar/podcasts/valUGspr23/session18slides.pdf Post class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session18Dtest.pdf Post class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session18Dsoln.pdf Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 9 · 1 hr 34 min

    Session 23: The Options to Expand and Abandon, Financial Flexibility and Distressed Equity

    We started this class by looking at the option to expand, where your capacity to enter or expand into new (big) markets can justify up-front bad investments and then at the option to abandon poorly performing investments. We then valued financial flexibility as an option, and argued that it was worth more to capital-constrained companies with unpredictable and high-value-added investments. We continued with our examination of equity in trouble, debt-laden companies. Given that the equity in these companies takes on the characteristics of an option, we teased out three implications: The equity in these companies will be valued as out-of-the-money options are and not as conventional stocks. Thus, they will retain their value, even in the face of daunting debt, and will become more valuable as the risk in the business increases and with longer term debt. Start of the class test: http://www.stern.nyu.edu/~adamodar/pdfiles/eqnotes/tests/realoptions2mod.pdf Slides: http://www.stern.nyu.edu/~adamodar/podcasts/valfall16/valsession23.pdf Post class test: http://www.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session23test.pdf Post class test solution: http://www.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session23soln.pdf Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 9 · 1 hr 32 min

    Session 17: The Financing Mix Trade off

    In this class, we started our discussion of the financing question by drawing the line between debt and equity: fixed versus residual claims, no control versus control, and then used a life cycle view of a company to talk about how much it should borrow. We then started on the discussion of debt versus equity by looking at the pluses of debt (tax benefits, added discipline) and its minuses (expected bankruptcy costs, agency cost and loss of financial flexibility). Even with the general discussion, we were able to look at why firms in some countries borrow more than others, why having more stable earnings can make a difference in how much you can borrow and why having intangible assets can affect your borrowing capacity. Slides: https://pages.stern.nyu.edu/~adamodar/podcasts/cfspr23/session17slides.pdf Post class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/cfovhds/postclass/session17test.pdf Post class test solution: https://pages.stern.nyu.edu/~adamodar/pdfiles/cfovhds/postclass/session17soln.pdf Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 8 · 58 min

    Session 22: The Option to Delay

    In this shortened session after the webcast, we looked at the option to delay and applied it to valuing patents and undeveloped natural resource reserves. Slides: http://www.stern.nyu.edu/~adamodar/podcasts/valfall16/valsession22.pdf Post class test: http://www.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session22Atest.pdf Post class test solution: http://www.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session22Asoln.pdf Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 8 · 1 hr 24 min

    Session 19: First Steps on Pricing

    We started the class by setting the stage of pricing companies, contrasting the pricing process with the value process. The rest of the class was our first foray into pricing, with why pricing is so much more common than intrinsic value and how multiples are just standardized prices. We also started on the first steps in deconstructing pricing, with the definitional and descriptional tests. Start of the class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/eqnotes/relval1test.pdf Slides: https://pages.stern.nyu.edu/~adamodar/podcasts/valUGspr23/session19slides.pdf Post class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session19Dtest.pdf Post class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session19Dsoln.pdf Learn more about your ad choices. Visit megaphone.fm/adchoices
  • October 8 · 11 min

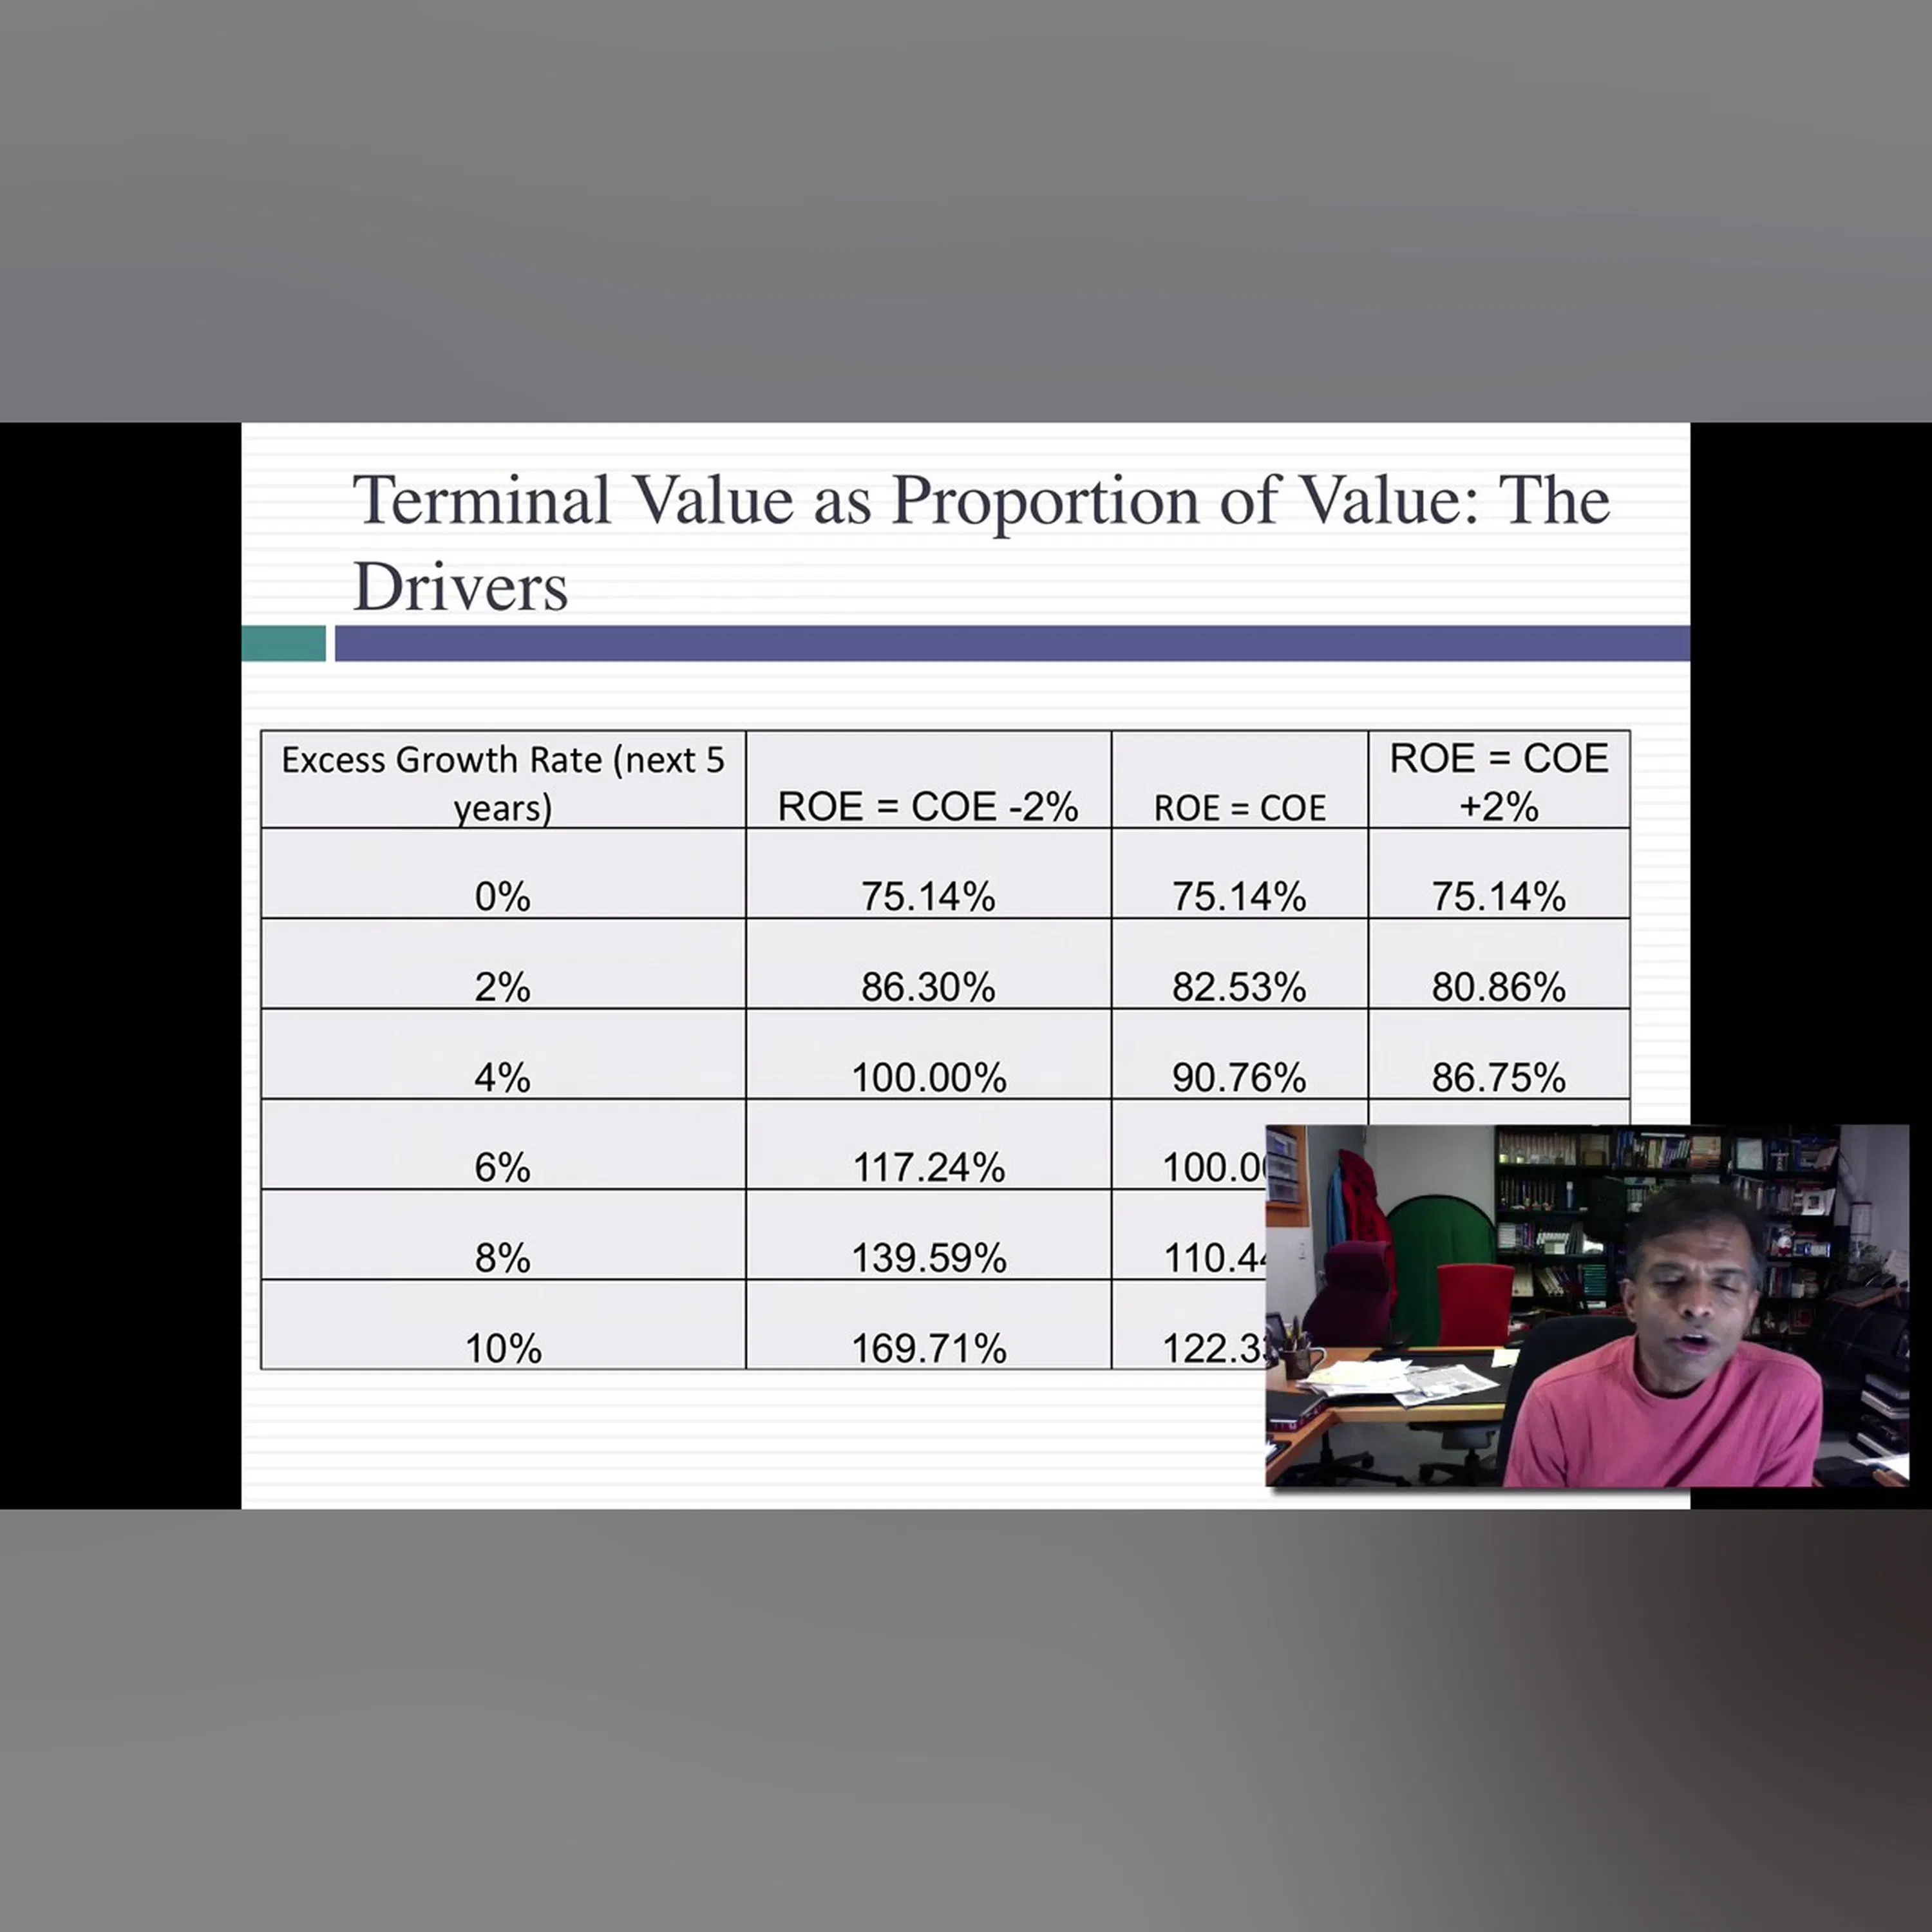
    Terminal Value Myth 5: The Terminal value ate my DCF!

    In a DCF of a business, the terminal value will account for a large proportion of value and this is viewed by some as a flaw in DCF and by others as a license to not worry about assumptions made during growth periods. Both presumptions are wrong. A DCF is a mirror of how you make money investing in stock, with the terminal value playing the role of capital gains (price appreciation). Also, the terminal value, though a high proportion of value, is heavily affected by your growth assumptions (about level & efficiency). Slides: http://www.stern.nyu.edu/~adamodar/pdfiles/blog/TermValyeMyth5.pdf Blog Post: http://aswathdamodaran.blogspot.com/2016/11/myth-55-terminal-value-ate-my-dcf.html Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 8 · 12 min

    Terminal Value Myth 4: Negative Growth Rates are impossible

    In this session, I confront the myth that you cannot do a DCF with negative growth rates and that the perpetual growth model will not work if you have negative growth. In fact, negative growth is more common among companies than we think and we need to use negative growth in our projections more frequently. Slides: http://www.stern.nyu.edu/~adamodar/pdfiles/blog/TermValyeMyth14.pdf Blog Post: http://aswathdamodaran.blogspot.com/2016/11/myth-54-negative-growth-rates-forever.html Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 7 · 1 hr 29 min

    Session 18: Optimizing Financing Mix

    We started this class by completing the debt trade off, by bringing in agency costs and financial flexibility, and looking at a financing hierarchy, starting with retained earnings as the most preferred and convertible preferred as the least preferred financing for firms. We looked at the Miller Modigliani theorem through the prism of the debt tradeoff and followed up by using the financing hierarchy that companies seem to move down, when they think about raising fresh financing. I then moved on to looking at how the cost of capital can be used to optimize the right mix of debt and equity. In effect, you estimate the costs of debt and equity at different debt ratios, and try to find the mix of debt and equity that minimizes your cost of capital. If you want to try your hand at using the spreadsheet to optimize debt ratio, try the following: http://www.stern.nyu.edu/~adamodar/pc/capstru.xlsx We will continue with this discussion next week. looking at limits to the approach, and variants. Slides: https://pages.stern.nyu.edu/~adamodar/podcasts/cfspr23/session18slides.pdf Post class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/cfovhds/postclass/session18test.pdf Post class test solution: https://pages.stern.nyu.edu/~adamodar/pdfiles/cfovhds/postclass/session18soln.pdf Learn more about your ad choices. Visit megaphone.fm/adchoices
  • October 7 · 15 min

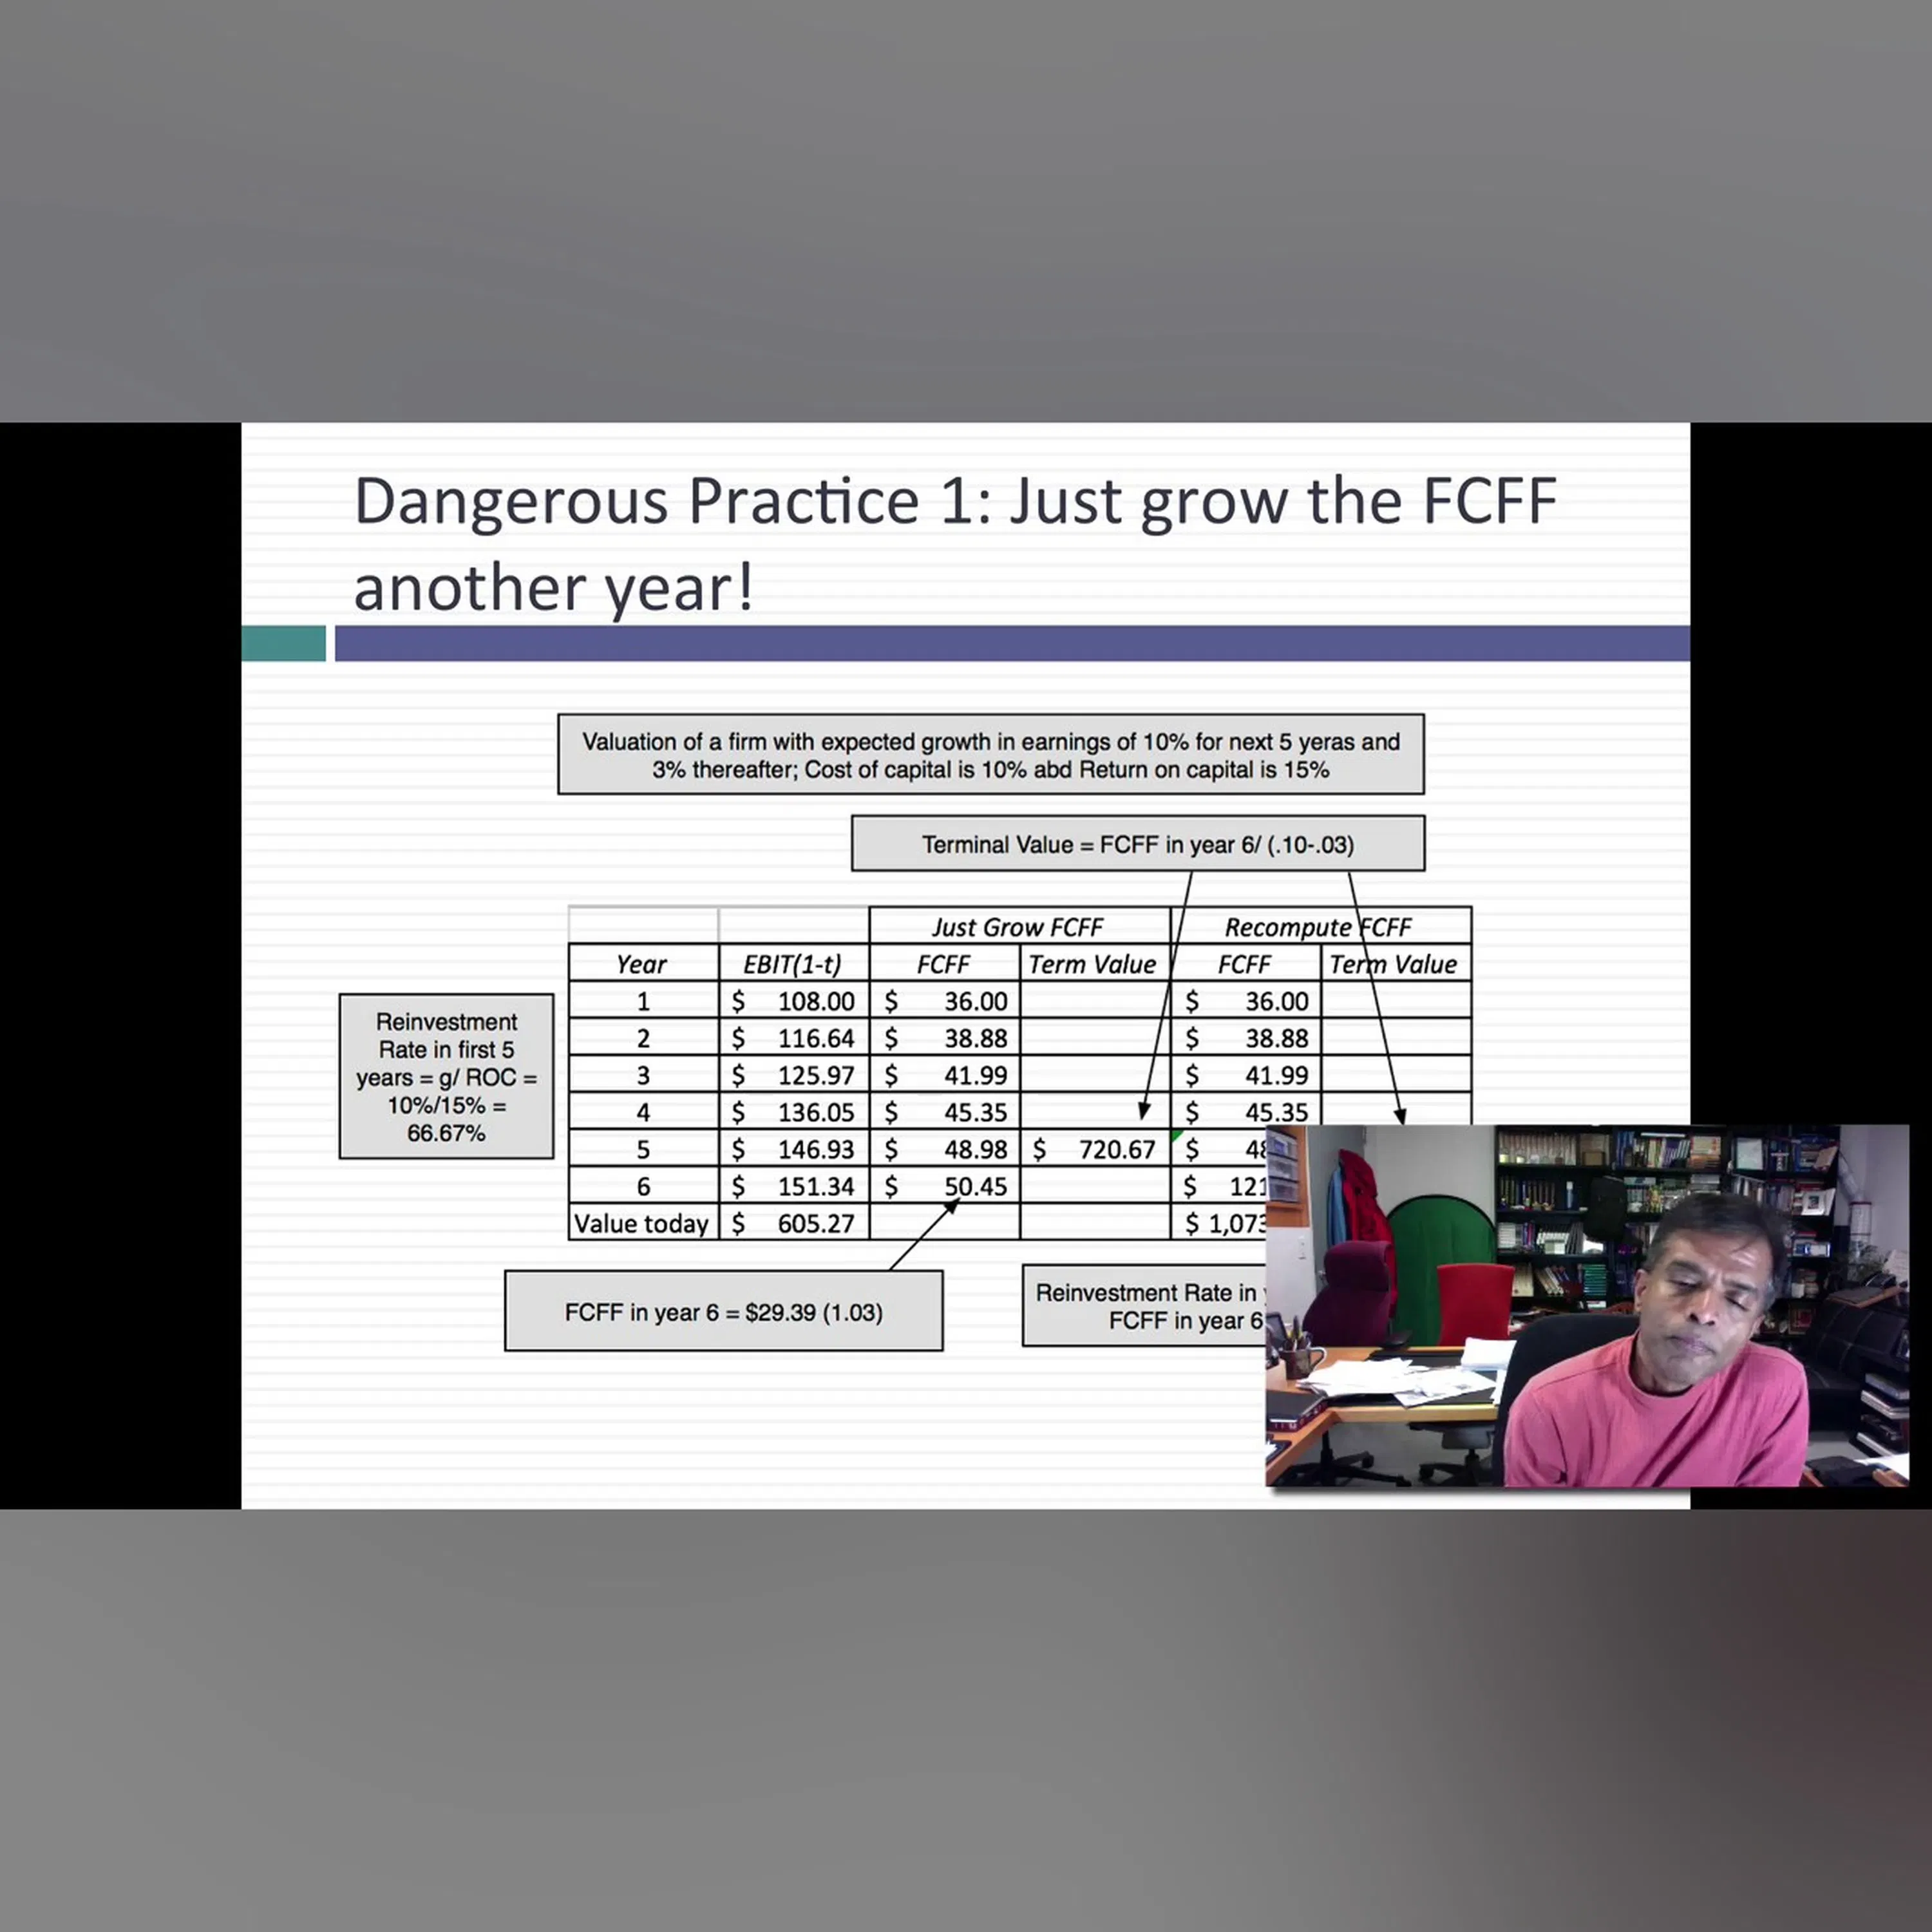
    Terminal Value Myth 3: Growth is good, more growth is better!

    In the perpetual growth model, increasing growth while holding all else constant will always increase value. That is the problem. If you follow consistency requirements, increasing growth will affect your cash flows and the effect of growth becomes ambiguous. It can increase, decrease or do nothing to value. Slides: http://www.stern.nyu.edu/~adamodar/pdfiles/blog/TermValyeMyth3.pdf Blog Post: http://aswathdamodaran.blogspot.com/2016/11/myth-53-growth-is-good-more-growth-is.html Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 7 · 1 hr 38 min

    Session 18: Deconstructing Multiples

    In this session, we continued with our discussion of pricing, starting with the analytics that drive PEG, PBV, EV/EBITDA and revenue multiples. During the session, I played the role of a naive equity research analyst, using sloppy pricing to push buy recommendations on stocks in a number of sectors, based purely on the level of multiples (low PE, low PBV etc.) and asking for pushback. I The bottom line, though, is that most companies that look cheap deserve to be cheap. The key to pricing is finding a mismatch between the pricing and the fundamentals (low PE & high growth, low PBB and high ROE, low EV to Sales and high margins). It is the basis for much of equity research, and takes the form of screens. If you are interested, I have a post that expands on the notion of screening. http://aswathdamodaran.blogspot.com/2012/06/passive-value-investing-screening-for.html Start of the class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/eqnotes/tests/relval2atest.pdf Slides: https://www.stern.nyu.edu/~adamodar/podcasts/valspr23/session18slides.pdf Post class test: https://www.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session18Btest.pdf Post class test solution: https://www.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session18Bsoln.pdf Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 7 · 13 min

    Terminal Value Myth 2: As g approaches r, it is to Infinity and beyond!

    Many analysts when they first see the perpetual growth model feel the call of Buzz Lightyear, since moving the growth rate towards the discount rate will make your terminal value explode before it implodes. In this session, I look at the constraints on growth in the terminal value equation and explain why I use the risk free rate as my cap on the growth rate. Slides: http://www.stern.nyu.edu/~adamodar/pdfiles/blog/TermValyeMyth2.pdf Blog Post: http://aswathdamodaran.blogspot.com/2016/11/myth-52-as-g-rto-infinity-and-beyond.html Learn more about your ad choices. Visit megaphone.fm/adchoices
  • October 6 · 1 hr 26 min

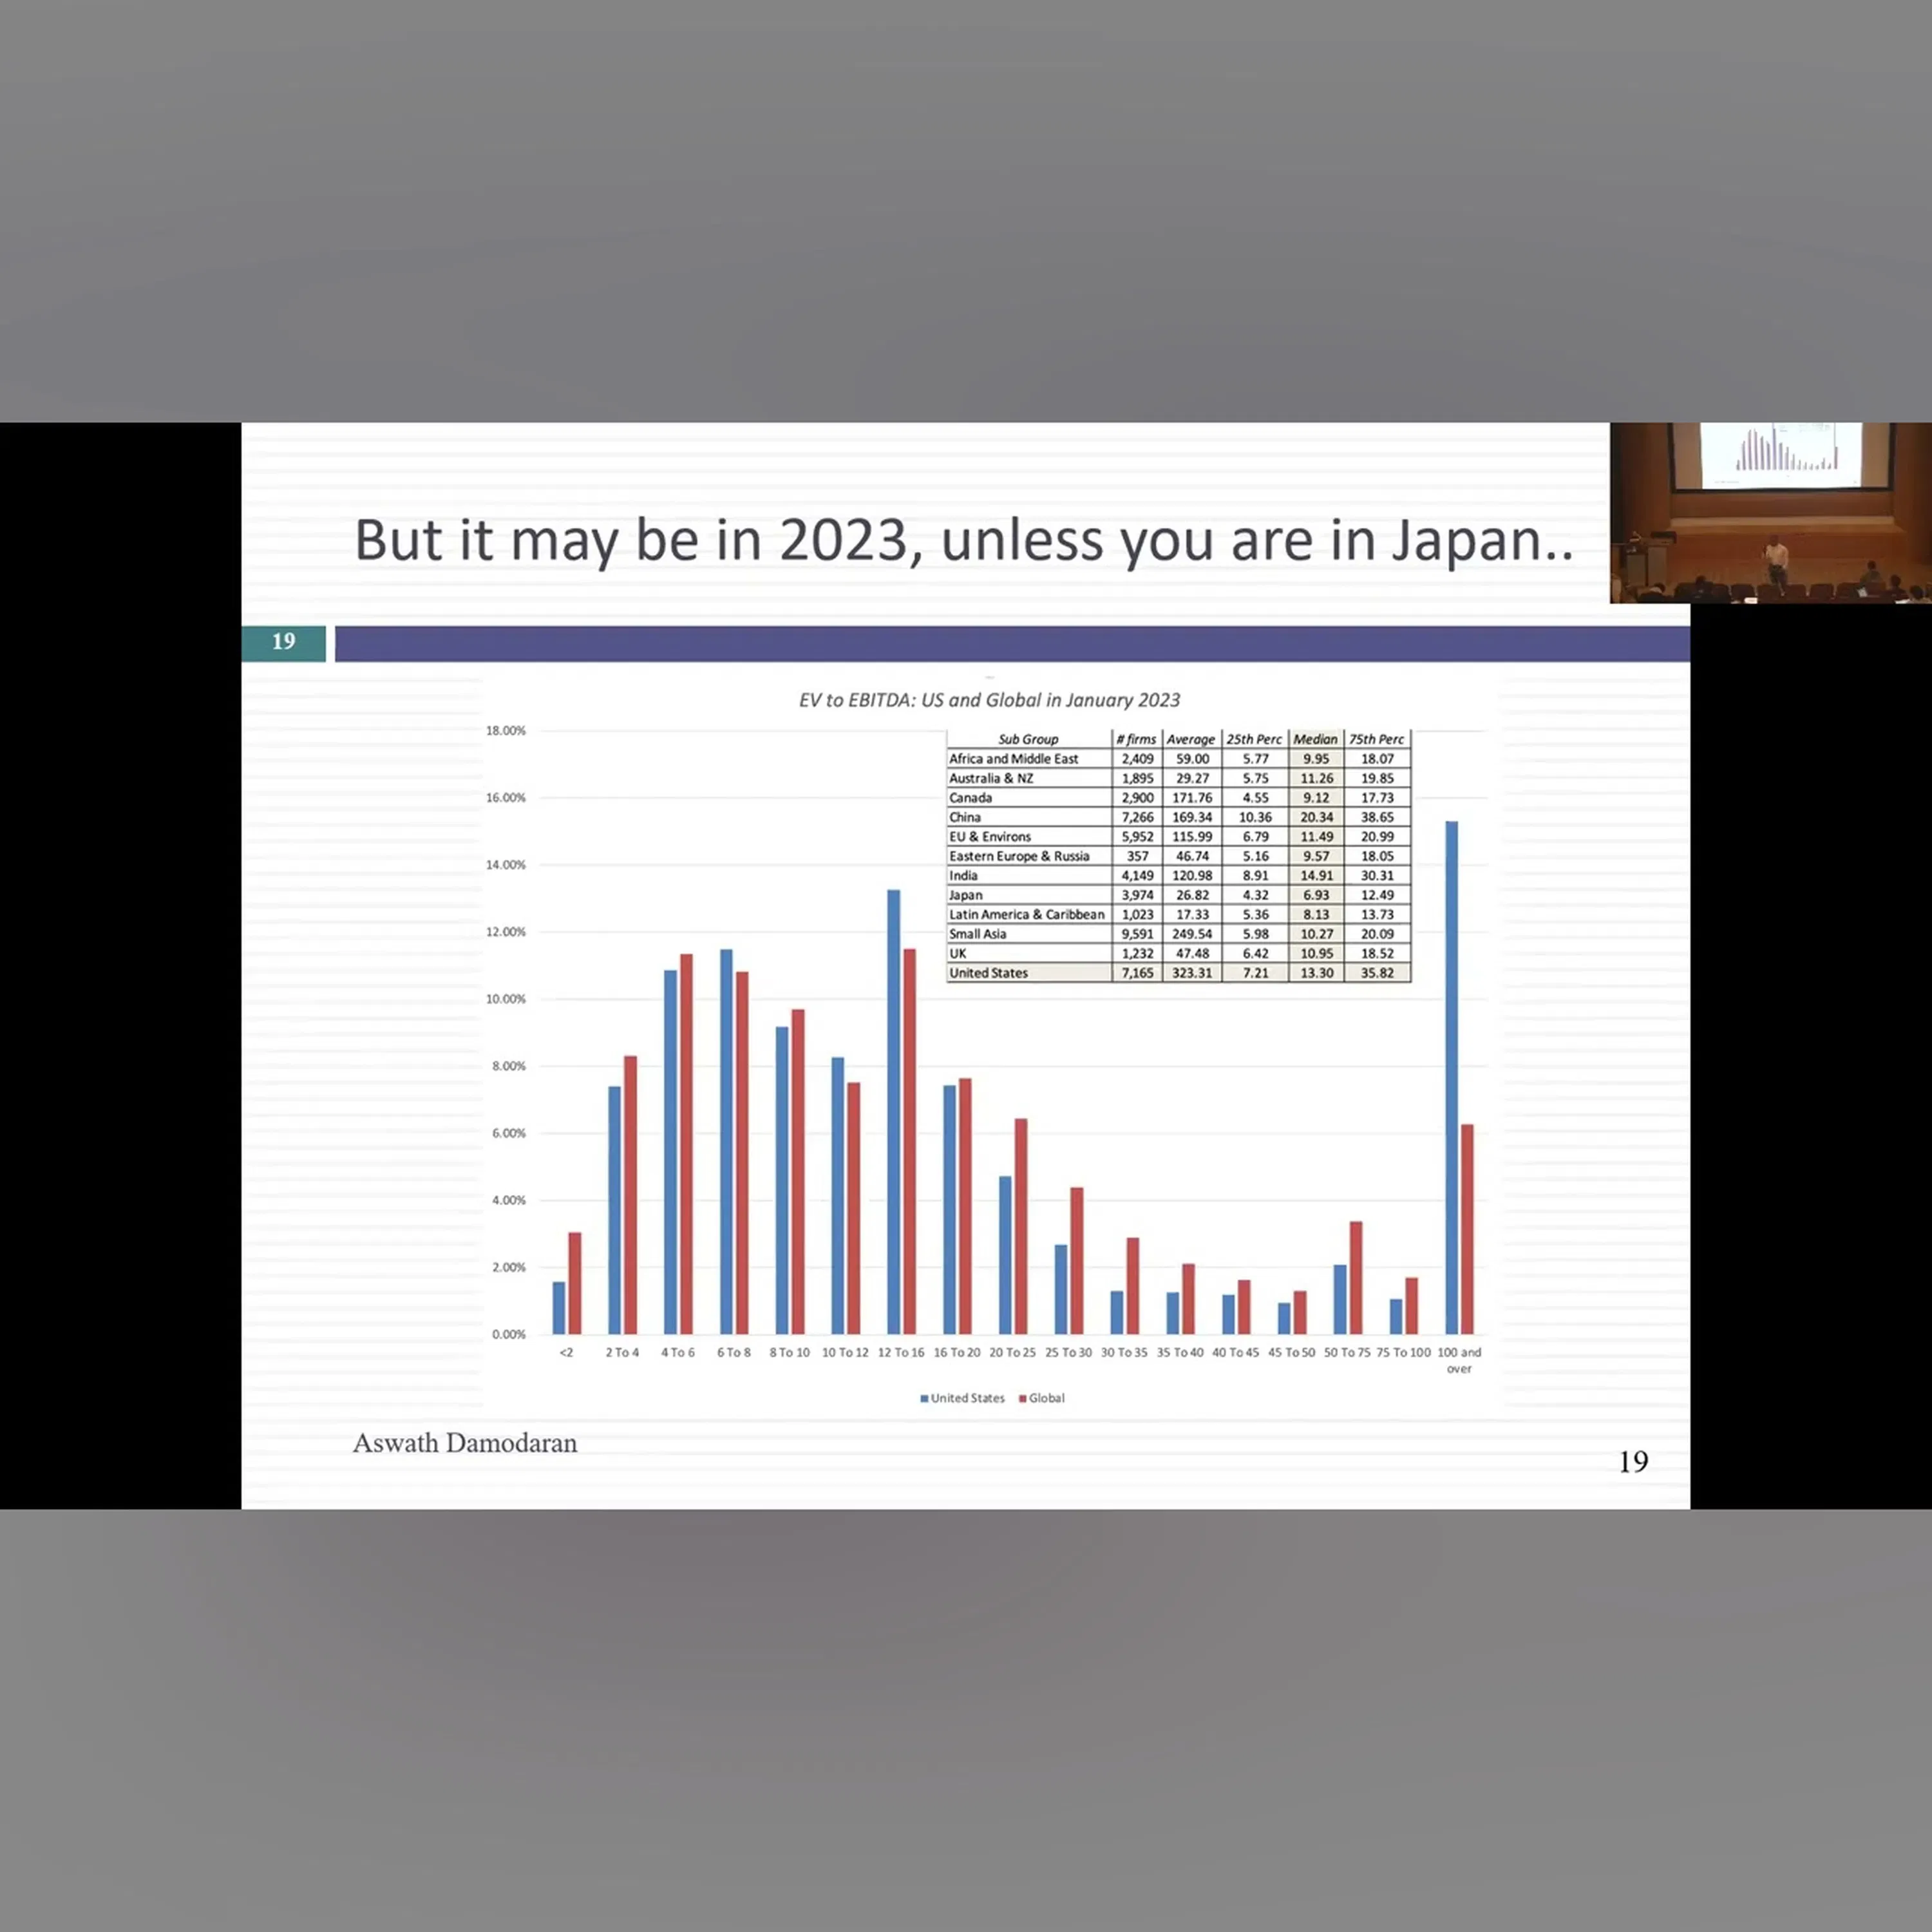
    Session 20: Analyzing Multiples

    In this session, we continued with our discussion of pricing, starting with the analytics that drive PEG, PBV, EV/EBITDA and revenue multiples. During the session, I played the role of a naive equity research analyst, using sloppy pricing to push buy recommendations on stocks in a number of sectors, based purely on the level of multiples (low PE, low PBV etc.) and asking for pushback. I The bottom line, though, is that most companies that look cheap deserve to be cheap. The key to pricing is finding a mismatch between the pricing and the fundamentals (low PE & high growth, low PBB and high ROE, low EV to Sales and high margins). It is the basis for much of equity research, and takes the form of screens. If you are interested, I have a post that expands on the notion of screening. http://aswathdamodaran.blogspot.com/2012/06/passive-value-investing-screening-for.html Start of the class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/eqnotes/relval2atest.pdf Slides: https://pages.stern.nyu.edu/~adamodar/podcasts/valUGspr23/session20slides.pdf Post class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session20Btest.pdf Post class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/eqnotes/postclass/session20Bsoln.pdf Learn more about your ad choices. Visit megaphone.fm/adchoices

  • October 6 · 9 min

    Terminal Value Myth 1: Don't believe in forever? You can't do DCF!

    In classrooms and textbooks, you are taught that there is only one way to estimate a terminal value and that is to assume cash flows grow at a constant rate forever. That is one way but it is not the only one. In this session, I look at two acceptable alternatives and one that should not (but unfortunately is). Slides: http://www.stern.nyu.edu/~adamodar/pdfiles/blog/TermValyeMyth1.pdf Blog Post: http://aswathdamodaran.blogspot.com/2016/11/myth-51-if-you-don-believe-in-forever.html Learn more about your ad choices. Visit megaphone.fm/adchoices

Showing 101–120 of 246 episodes