Session 9: Betas - Drivers and Determinants
transcript
show notes
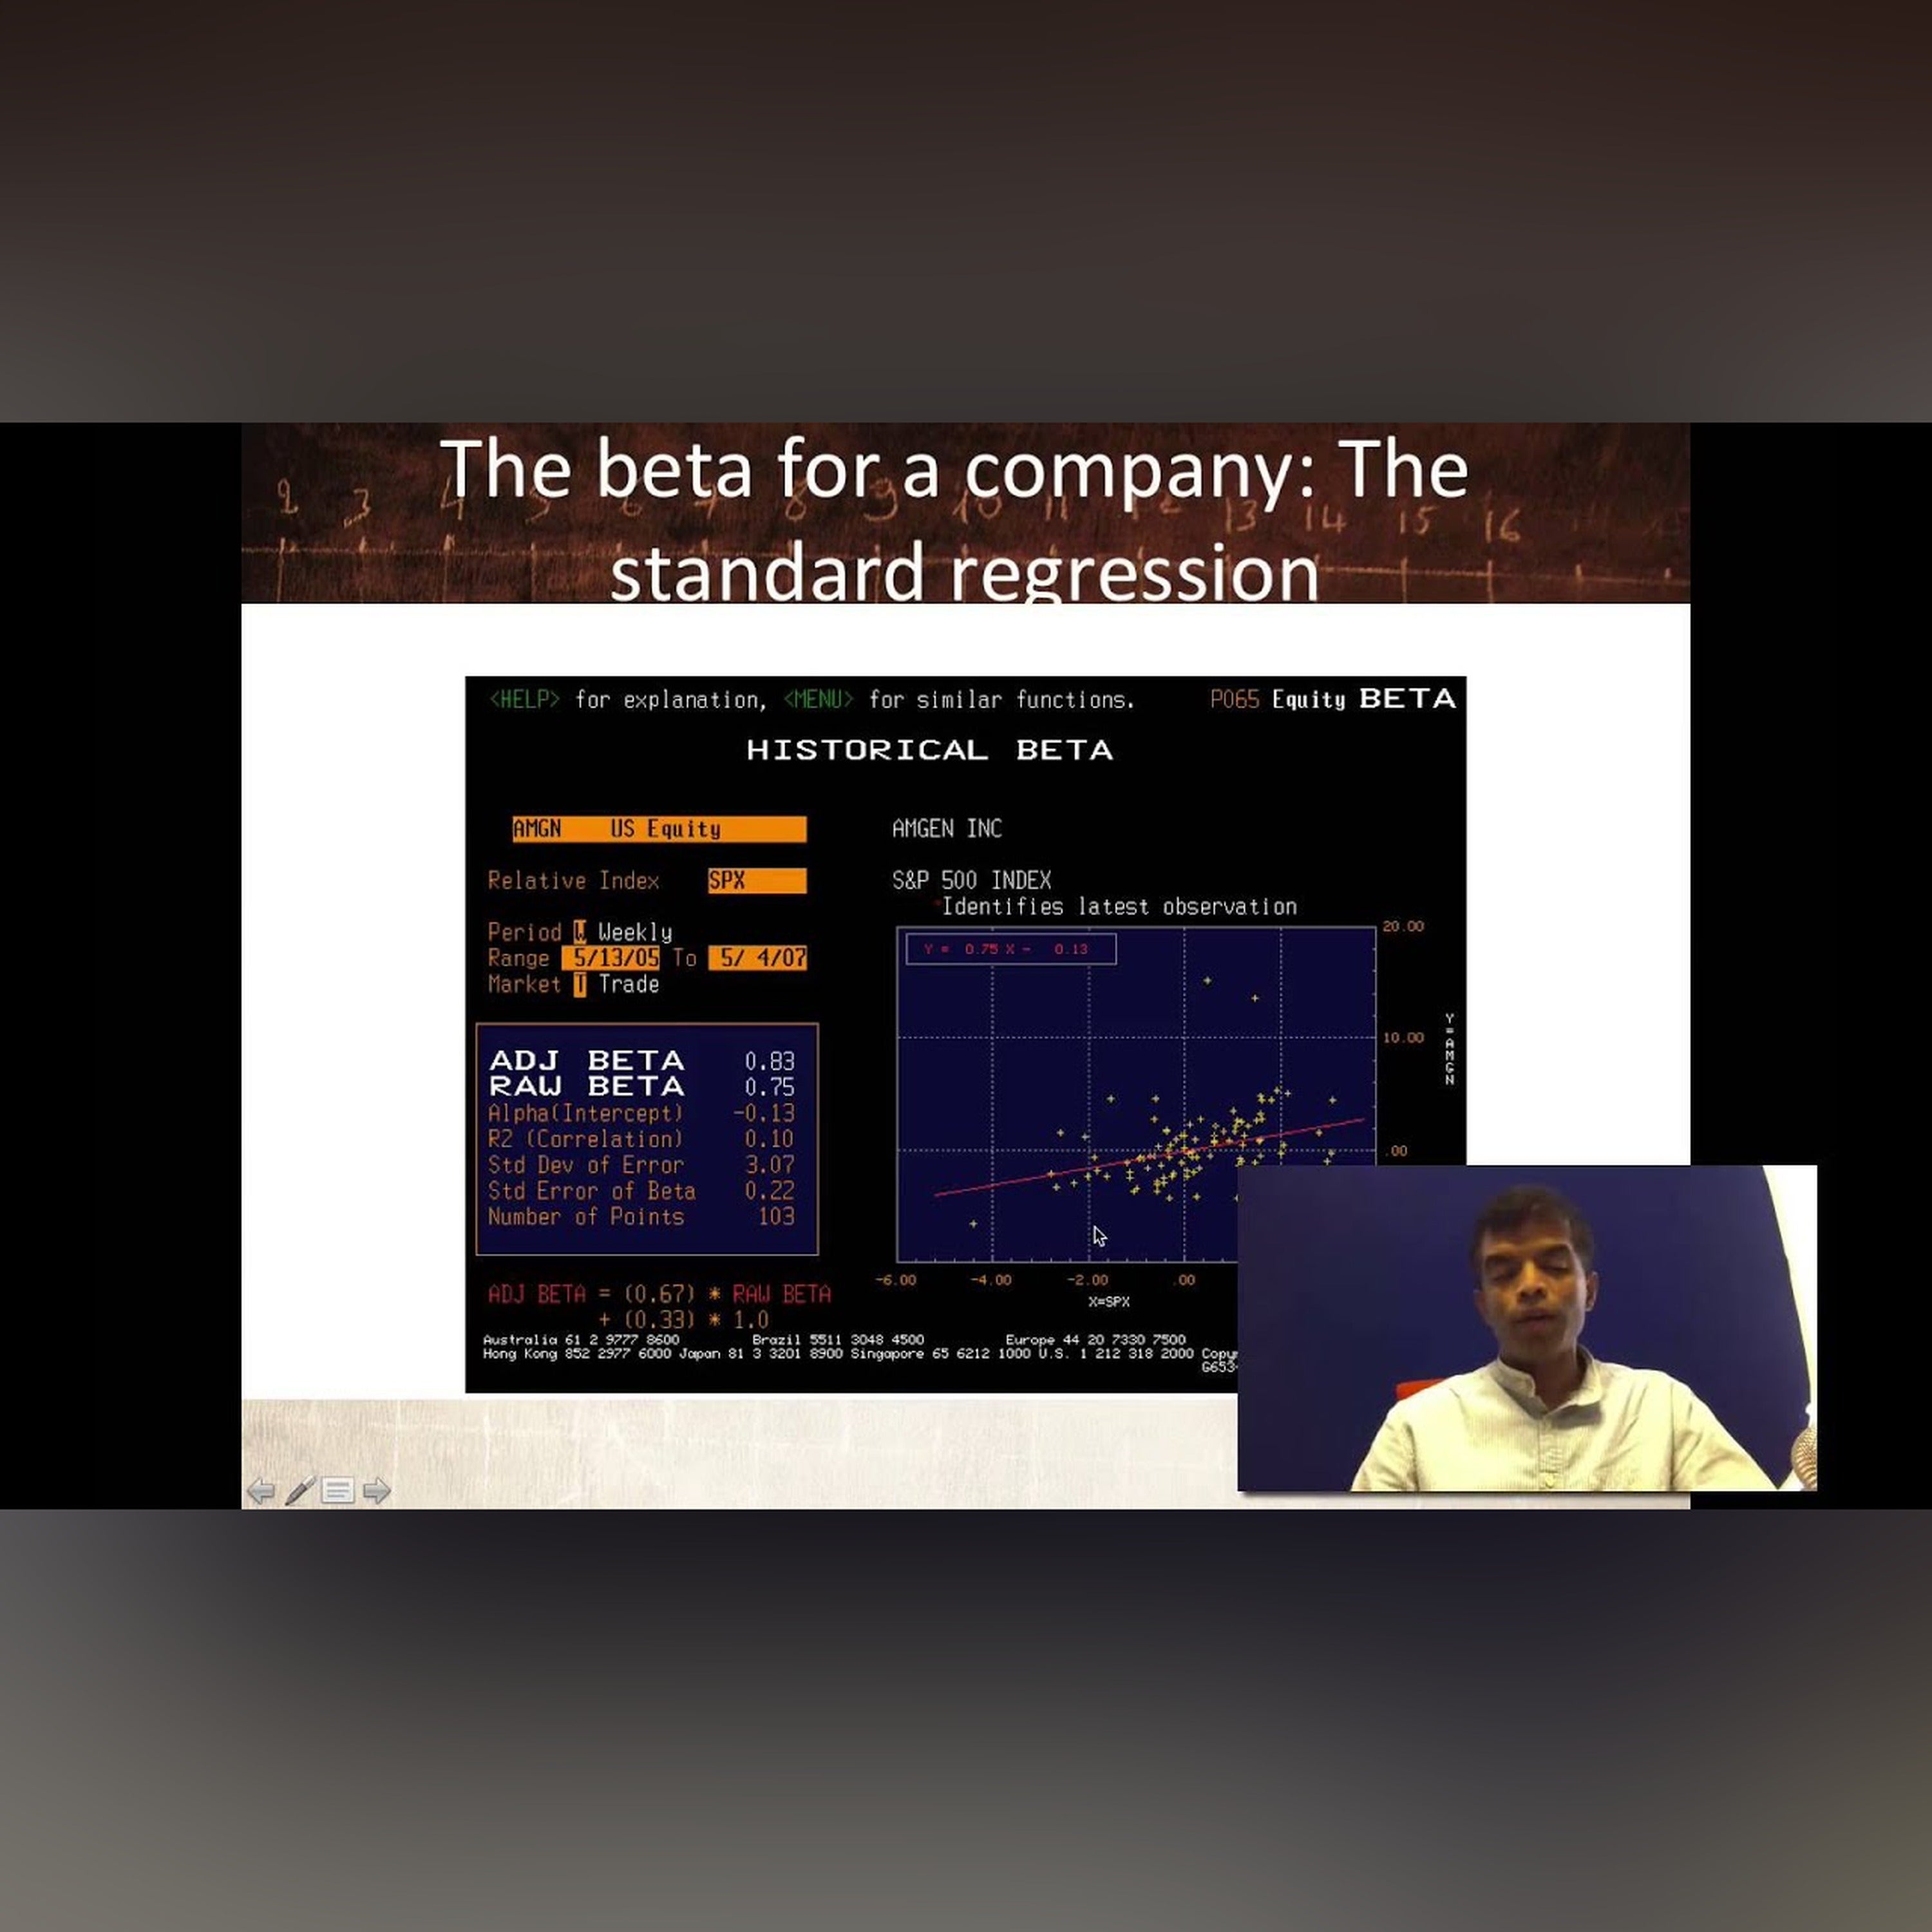
In this class, we looked past regression betas at how the choices companies make about the businesses they enter can determine their betas.. Summarizing the class, here is what we listed as the three determinants of betas:
1. Betas are determined in large part by the nature of your business. While I am not an expert on strategy, marketing or productions, decisions that you make in those disciplines can affect your beta. Thus, your decision to go for a price leader as opposed to a cost leader (I hope I am getting my erminology right) or build up a brand name has implications for your beta. As some of you probably realized today, the discussion about whether your product or service is discretionary is tied to the elasticity of its demand (an Econ 101 concept that turns out to have value)... Products and services with elastic demand should have higher betas than products with inelastic demand. And if you do get a chance, try to make that walk down Fifth Avenue...
2. Your cost structure matters. The more fixed costs you have as a firm, the more sensitive your operating income becomes to changes in your revenues.
3. Financial leverage: When you borrow money, you create a fixed cost (interest expenses) that makes your equity earnings more volatile. Thus, the equity beta in a safe business can be outlandishly high if has lots of debt. The levered beta equation we went through is a staple for this class and we will revisit it again and again. So, start getting comfortable with it.
I know that the last part of this class was a grind with numbers building on top of numbers. In specific, we looked at how to estimate the beta for not only a company but its individual businesses by building up to a beta, rather than trusting a single regression. With Disney, we estimated a beta for each of the five businesses it was in, a collective beta for Disney's operating businesses and a beta for Disney as a company (including its cash).
Slides: https://pages.stern.nyu.edu/~adamodar/podcasts/cfspr23/session9slides.pdf
Post class test: https://pages.stern.nyu.edu/~adamodar/pdfiles/cfovhds/postclass/session9atest.pdf
Post class test solution: https://pages.stern.nyu.edu/~adamodar/pdfiles/cfovhds/postclass/session9asoln.pdf
Learn more about your ad choices. Visit megaphone.fm/adchoices
- https://pages.stern.nyu.edu/~adamodar/podcasts/cfspr23/session9slides.pdfpages.stern.nyu.edu
- https://pages.stern.nyu.edu/~adamodar/pdfiles/cfovhds/postclass/session9atest.pdfpages.stern.nyu.edu
- https://pages.stern.nyu.edu/~adamodar/pdfiles/cfovhds/postclass/session9asoln.pdfpages.stern.nyu.edu
- megaphone.fm/adchoicesmegaphone.fm