Skip to content
Artwork for The Innovation Attorney Podcast
The Innovation Attorney Podcast · September 25 · 13 min

How Do Preference Terms Erode Founder Control

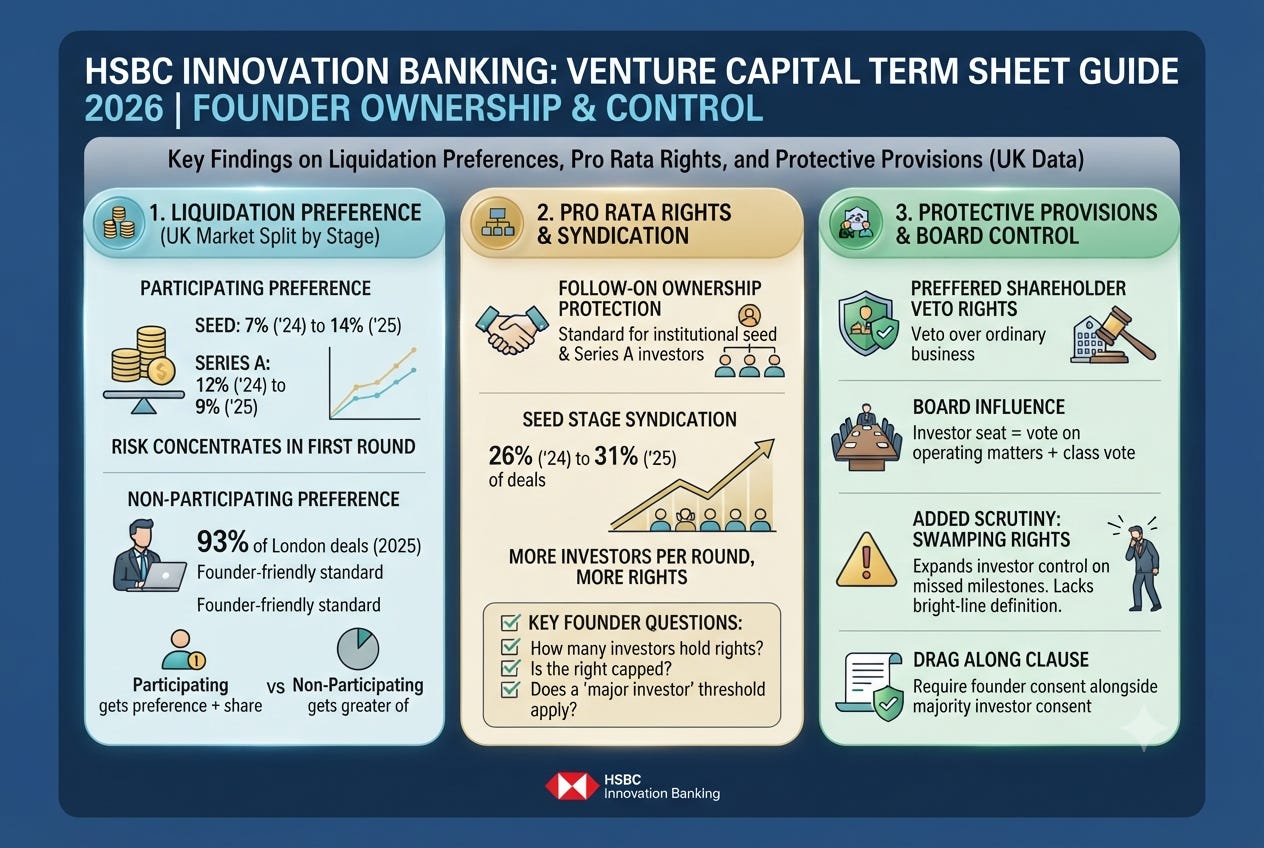
HSBC Innovation Banking’s 2026 Venture Capital Term Sheet Guide, compiled from 711 completed United Kingdom deals worth roughly 14.3 billion United States Dollars, shows that liquidation preference, pro rata rights, and protective provisions do more to determine a founder’s control of the company than the valuation printed on the front page of the term sheet. The clause most seed stage founders skip past in 2026 is the swamping right: a provision that lets an investor’s consent rights expand automatically the moment the company misses a milestone or runs short of cash. HSBC Innovation Banking singles out swamping rights for added scrutiny in its 2026 guide, and the timing fits the rest of the data. The same guide found that participating preference shares, the feature that lets an investor collect its investment back and then share in what remains for common stockholders, nearly doubled at seed stage in the United Kingdom, moving from 7 percent of deals in 2024 to 14 percent in 2025. A founder signing a seed term sheet in 2026 is more likely than a founder signing in 2024 to be handing an investor both a bigger claim on exit proceeds and a bigger claim on decision making the moment the business hits a rough patch. Liquidation preference is the mechanism, not the headline. It sets the order in which proceeds are paid out when the company sells, merges, or dissolves, and it runs on two variables: the multiple, usually 1.0x the original investment, and whether the preference participates in what is left after that multiple is paid. HSBC Innovation Banking’s companion United States guide, released May 14, 2026 from more than 500 signed deals, found a 1.0x multiple in 93 percent of deals and a non participating structure in 86 percent, a tighter and more standardized market than the United Kingdom currently offers. Delaware General Corporation Law Section 242(b)(2) requires a separate vote of the preferred stockholders as a class before a company can amend its certificate of incorporation in a way that alters their rights, which is why a liquidation preference negotiated at the term sheet stage becomes binding the moment it is written into the charter. The United Kingdom data splits sharply by stage and by geography. At Series A, participating preference shares fell from 12 percent to 9 percent of deals, meaning the market moved toward founders as companies matured, even as it moved away from them at seed. London term sheets carried non participating preference shares, the founder favorable structure, in 93 percent of deals, the most favorable regional figure HSBC Innovation Banking’s 2026 guide reports. A founder raising outside London, or raising a seed round anywhere, is negotiating against a materially different set of market norms than the guide’s headline numbers suggest, and reading the guide as a single national average would hide that split. Pro rata rights work differently from a liquidation preference, and a first time founder often conflates the two. A pro rata right, typically granted in an investor rights agreement built on the National Venture Capital Association’s model form, lets an existing investor buy enough shares in a future round to hold its percentage steady. It does not dilute a founder beyond what the new round’s math already requires, but it does determine how much room is left in that round for new capital. HSBC Innovation Banking’s 2026 guide reports that seed stage syndication rose from 26 percent to 31 percent of deals between 2024 and 2025, which means more investors per round are claiming pro rata rights at exactly the stage where the capitalization table has the least room to absorb them. Protective provisions are the clause that decides who runs the company after the money arrives, and they are frequently the least read page of the term sheet. The standard National Venture Capital Association list gives preferred stockholders, voting as a class, a veto over amendments to the certificate of incorporation, new securities senior to or on par with the existing preferred, debt above a stated threshold, a sale of the company, and dissolution. HSBC Innovation Banking’s 2026 guide adds a caution beyond that standard list: a low threshold for a drag along clause, the provision compelling minority shareholders into an approved sale, should require both founder and majority investor consent rather than majority investor consent alone. In thirty years counseling technology companies through their first priced round, I have watched founders spend a week negotiating fifty basis points of valuation and five minutes reading the protective provisions schedule, the two pages of the term sheet that actually decide who controls the board once a milestone slips. A founder preparing for a first negotiation in 2026 should reverse that order: model the exit waterfall under both a 1.0x non participating preference and a participating preference before caring about the valuation headline, confirm whether existing investors hold uncapped pro rata rights, and read the protective provisions schedule for a swamping right or a drag along threshold that does not require founder consent. Enterprise Investment Scheme and Venture Capital Trust investors, now present in 29 percent of United Kingdom seed and Series A rounds according to HSBC Innovation Banking’s 2026 guide, typically bring stricter reporting and consent requirements than institutional venture funds. A founder who treats every term sheet as interchangeable will miss that difference until it shows up as an unexpected consent right eighteen months into the company’s life. The guide is a benchmark, not a term sheet template, and it should be used as one. A founder with a single offer on the table has almost no bargaining power to move any of these three clauses. A founder with two or three term sheets, even imperfect ones, can point to HSBC Innovation Banking’s own 2026 data and ask a specific, answerable question: why does this preference carry a participation feature when 93 percent of London deals this year did not, or why does this drag along clause bind at a majority investor vote alone when the guide itself flags that structure as one investors are pulling back from. The next piece in this series works through an actual seed stage capitalization table before and after a participating preference and a broad based weighted average anti dilution provision, showing in dollars what a swamping right costs a founder who misses a single milestone. Interested in analysis about the intersection of venture capital, tech, artificial intelligence, public policy and the law? Check out my Substack channel. https://theinnovationattorney.substack.com/ This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit theinnovationattorney.substack.com/subscribe

0:00-13:20

transcript

No transcript — this publisher did not publish one.

show notes

HSBC Innovation Banking’s 2026 Venture Capital Term Sheet Guide, compiled from 711 completed United Kingdom deals worth roughly 14.3 billion United States Dollars, shows that liquidation preference, pro rata rights, and protective provisions do more to determine a founder’s control of the company than the valuation printed on the front page of the term sheet.

The clause most seed stage founders skip past in 2026 is the swamping right: a provision that lets an investor’s consent rights expand automatically the moment the company misses a milestone or runs short of cash. HSBC Innovation Banking singles out swamping rights for added scrutiny in its 2026 guide, and the timing fits the rest of the data. The same guide found that participating preference shares, the feature that lets an investor collect its investment back and then share in what remains for common stockholders, nearly doubled at seed stage in the United Kingdom, moving from 7 percent of deals in 2024 to 14 percent in 2025. A founder signing a seed term sheet in 2026 is more likely than a founder signing in 2024 to be handing an investor both a bigger claim on exit proceeds and a bigger claim on decision making the moment the business hits a rough patch.

Liquidation preference is the mechanism, not the headline. It sets the order in which proceeds are paid out when the company sells, merges, or dissolves, and it runs on two variables: the multiple, usually 1.0x the original investment, and whether the preference participates in what is left after that multiple is paid. HSBC Innovation Banking’s companion United States guide, released May 14, 2026 from more than 500 signed deals, found a 1.0x multiple in 93 percent of deals and a non participating structure in 86 percent, a tighter and more standardized market than the United Kingdom currently offers. Delaware General Corporation Law Section 242(b)(2) requires a separate vote of the preferred stockholders as a class before a company can amend its certificate of incorporation in a way that alters their rights, which is why a liquidation preference negotiated at the term sheet stage becomes binding the moment it is written into the charter.

The United Kingdom data splits sharply by stage and by geography. At Series A, participating preference shares fell from 12 percent to 9 percent of deals, meaning the market moved toward founders as companies matured, even as it moved away from them at seed. London term sheets carried non participating preference shares, the founder favorable structure, in 93 percent of deals, the most favorable regional figure HSBC Innovation Banking’s 2026 guide reports. A founder raising outside London, or raising a seed round anywhere, is negotiating against a materially different set of market norms than the guide’s headline numbers suggest, and reading the guide as a single national average would hide that split.

Pro rata rights work differently from a liquidation preference, and a first time founder often conflates the two. A pro rata right, typically granted in an investor rights agreement built on the National Venture Capital Association’s model form, lets an existing investor buy enough shares in a future round to hold its percentage steady. It does not dilute a founder beyond what the new round’s math already requires, but it does determine how much room is left in that round for new capital. HSBC Innovation Banking’s 2026 guide reports that seed stage syndication rose from 26 percent to 31 percent of deals between 2024 and 2025, which means more investors per round are claiming pro rata rights at exactly the stage where the capitalization table has the least room to absorb them.

Protective provisions are the clause that decides who runs the company after the money arrives, and they are frequently the least read page of the term sheet. The standard National Venture Capital Association list gives preferred stockholders, voting as a class, a veto over amendments to the certificate of incorporation, new securities senior to or on par with the existing preferred, debt above a stated threshold, a sale of the company, and dissolution. HSBC Innovation Banking’s 2026 guide adds a caution beyond that standard list: a low threshold for a drag along clause, the provision compelling minority shareholders into an approved sale, should require both founder and majority investor consent rather than majority investor consent alone.

In thirty years counseling technology companies through their first priced round, I have watched founders spend a week negotiating fifty basis points of valuation and five minutes reading the protective provisions schedule, the two pages of the term sheet that actually decide who controls the board once a milestone slips. A founder preparing for a first negotiation in 2026 should reverse that order: model the exit waterfall under both a 1.0x non participating preference and a participating preference before caring about the valuation headline, confirm whether existing investors hold uncapped pro rata rights, and read the protective provisions schedule for a swamping right or a drag along threshold that does not require founder consent.

Enterprise Investment Scheme and Venture Capital Trust investors, now present in 29 percent of United Kingdom seed and Series A rounds according to HSBC Innovation Banking’s 2026 guide, typically bring stricter reporting and consent requirements than institutional venture funds. A founder who treats every term sheet as interchangeable will miss that difference until it shows up as an unexpected consent right eighteen months into the company’s life.

The guide is a benchmark, not a term sheet template, and it should be used as one. A founder with a single offer on the table has almost no bargaining power to move any of these three clauses. A founder with two or three term sheets, even imperfect ones, can point to HSBC Innovation Banking’s own 2026 data and ask a specific, answerable question: why does this preference carry a participation feature when 93 percent of London deals this year did not, or why does this drag along clause bind at a majority investor vote alone when the guide itself flags that structure as one investors are pulling back from.

The next piece in this series works through an actual seed stage capitalization table before and after a participating preference and a broad based weighted average anti dilution provision, showing in dollars what a swamping right costs a founder who misses a single milestone.

Interested in analysis about the intersection of venture capital, tech, artificial intelligence, public policy and the law? Check out my Substack channel. https://theinnovationattorney.substack.com/


This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit theinnovationattorney.substack.com/subscribe
links1